Greetings from Mestia, Georgia, in the heart of Svaneti and not far from Ushguli — one of the highest populated settlements in Europe, sitting at roughly 2,050–2,200 metres above sea level.
This weekend we escaped Tbilisi for a road trip to Svaneti with our friend and driver, Vazha. After an overnight stop in Kutaisi and a long drive deeper into the Caucasus, we finally reached Mestia.
Svaneti really is one of those places that feels different from almost anywhere else: dramatic mountain scenery, medieval Svan defensive towers, tiny villages and a distinct local culture that has survived for centuries. It is remote, occasionally inconvenient and absolutely worth the journey.
If you haven’t been here yet, I can highly recommend putting Svaneti on your Georgia travel list.
Mountains aside, the markets are still open and the options portfolio does not take weekends off. Welcome to Week 76 of our stock options portfolio review.
Portfolio Performance
On September 18, 2026, our latest portfolio snapshot stood at $13,706, representing a 1.15% decrease week over week.
The $14,000 milestone remains within reach. We briefly came very close during the previous weeks, but markets have their own sense of humour — especially when you start paying too much attention to round numbers.
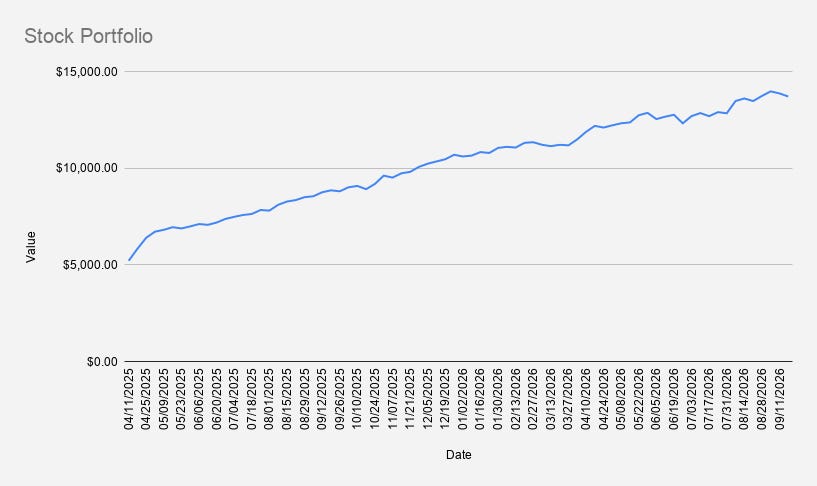
The portfolio is now up 33.03% year to date. For comparison, the S&P 500 is up roughly 11% in 2026, while NVDA has also delivered a positive year so far.
The important point, however, is not simply that the portfolio is ahead of the benchmarks. Our returns come with a very different risk profile. We actively sell option premium, use margin, roll positions when necessary and occasionally accept assignment. That can improve returns, but it also means taking risks that a passive index investor does not face.
A Relatively Quiet Week — With a Little Drama
There wasn’t an enormous amount of trading this week, although Monday provided enough activity to keep things interesting.
We rolled the NVDA credit spread further out, converted the BAC credit spread into a cash-secured put and continued watching NFLX move lower — which is exactly what we want while holding a November bear call spread.
A few positions also quietly did their job and disappeared. Our ARCC and HEL/STERV spreads from the previous week expired worthless, allowing us to keep the premium collected when the trades were opened.
Sometimes the best options trade is the one that expires without requiring any additional attention.
Current Options Positions
NVDA SEP 25, 2026 210/190 Bull Put Credit Spread
BMY OCT 16, 2026 57.5/52.5 Bull Put Credit Spread
BAC NOV 20, 2026 57.5 Cash-Secured Put
NFLX NOV 20, 2026 85/105 Bear Call Spread
LHA FRA DEC 18, 2026 7 Cash-Secured Put (EUR)
NVDA JUN 17, 2027 $125 Covered Call
NFLX DEC 17, 2027 64 Cash-Secured Put
Options Income and Reinvestment
Total options premium collected this week reached $94.
As usual, part of that income was recycled back into the portfolio rather than simply sitting as cash. This week we added 0.1 BAC share, 0.1 NFLX share, 1 NU share and 0.1 NVDA share.
These purchases are deliberately small. The idea is not to predict the perfect entry price, but to gradually turn options income into ownership of businesses we are comfortable holding over a longer period.
Starting a Position in NU
NU is a new addition to the portfolio.
I recently started researching companies trading below $100 that could potentially offer an attractive combination of growth and long-term compounding. During that research, Nu Holdings caught my attention and I decided to begin building a position gradually rather than making a large initial purchase.
Nu Holdings is the parent company behind Nubank, the digital financial-services platform that originated in Brazil and has expanded across Latin America. What makes the company interesting to me is the combination of a large addressable market, digital-first cost structure and continued customer growth.
That does not make NU a guaranteed long-term winner, of course. Fast-growing financial companies come with their own risks, including credit quality, regulation, competition, currency movements and valuation. For now, the plan is simple: accumulate slowly, follow the business and reassess the thesis as new financial results arrive.
Margin Update
The margin balance has decreased slightly to −$2,691.
At this week’s premium generation of $94, it would theoretically take around 29 weeks to eliminate that balance if every dollar of options income were directed toward reducing margin and weekly income remained unchanged.
Of course, markets do not produce identical weekly income. Volatility changes, positions get rolled, shares get assigned and some premium is deliberately reinvested into additional holdings. So the 29-week figure is better viewed as a simple reference point rather than a forecast.
The broader goal remains to keep the margin manageable while allowing the portfolio to compound.
What We Are Watching Next Week
The immediate focus next week will be the NVDA $210/$190 bull put spread expiring September 25.
NVDA remains above our short strike for now, but with short-dated options there is little reason to become complacent. A sharp move in the underlying can change the risk profile quickly.
If the position comes under pressure, the preferred approach remains the same: evaluate whether rolling forward and/or adjusting the strikes makes economic sense, preferably while collecting additional credit. Rolling simply to postpone a loss is not a strategy; the new position still needs to offer an acceptable risk/reward setup.
We will also continue watching BAC and NFLX. With the BAC short put, assignment would not necessarily be an undesirable outcome, since owning the shares would give us the possibility of moving into covered-call selling. Meanwhile, continued weakness in NFLX would benefit the existing November bear call spread.
The Bottom Line
Week 76 was not spectacular, and that is perfectly fine.
The portfolio slipped 1.15% to $13,706, yet remains up 33.03% for the year. We collected another $94 in option premium, reduced margin slightly, added small amounts of BAC, NFLX, NVDA and NU, and allowed several previous positions to expire worthless.
The $14,000 milestone is still sitting just ahead of us. There is no need to force it. The objective remains the same as it has been throughout this experiment: collect premium, manage risk, gradually accumulate assets and let compounding do as much of the heavy lifting as possible.
And for this particular weekend, there are worse places to watch the portfolio fluctuate than from the mountains of Svaneti.